

404
+1-313-307-4176

Titanium Alloys Market | 2026-2034
Titanium Alloys Market Size, Share, Trend, Forecast, Competitive Landscape & Growth Opportunities: 2026-2034
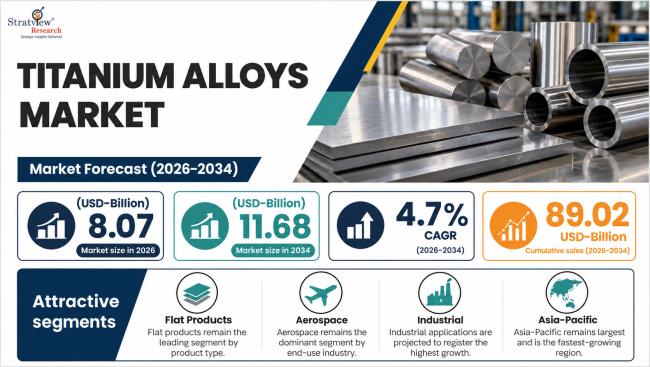
"The titanium alloys market is expected to reach USD 8.07 billion in 2026, growing 5.9% over 2025, and is projected to reach USD 11.68 billion by 2034, registering a CAGR of 4.7% during 2026–2034. The titanium alloys market is primarily driven by rising commercial aircraft production, continued defense aircraft procurement, and expanding demand for titanium alloys in medical implant applications."
The titanium alloys market was valued at USD 7.62 billion in 2025 and is expected to reach USD 8.07 billion in 2026, representing a year-on-year growth of 5.9%.
During the forecast period (2026–2034), the market is projected to grow at a CAGR of 4.7%, reaching USD 11.68 billion by 2034.
Asia-Pacific is expected to remain the largest market, followed by North America and then Europe over the forecast period.
Aerospace is estimated to remain the biggest procurer of titanium alloys in the years to come, whereas industrial applications are projected to register the highest growth during the forecast period,
Flat products are expected to remain the leading product type; along with that, tubes are projected to be the fastest-growing product type.
"As per the Senior Analyst at Stratview Research, the titanium alloys market is expected to create a cumulative sales opportunity of USD 89.02 billion during 2026-2034. During the upcoming years, Aerospace, Flat Products, Industrial, and Asia-Pacific are some of the high-opportunity segments to bank upon."
Sharpen Your Strategies to Explore this USD 85 Billion+ Opportunity. Get a Free Sample of Our Report: "Here".
Have a look at the sales opportunities presented by the titanium alloys market in terms of growth and market forecast.
|
Market Statistics |
Value (in USD Billion) |
Market Growth (%) |
|
Market Size in 2025 |
USD 7.62 billion |
- |
|
Market Size in 2026 |
USD 8.07 billion |
YoY Growth in 2026: 5.9% |
|
Market Size in 2034 |
USD 11.68 billion |
CAGR 2026-2034: 4.7% |
|
Cumulative Sales Opportunity during 2026-2034 |
USD 89.02 billion |
- |
Want to Explore the Market Opportunities? Get a Free Sample "Here".
The global titanium alloys market is influenced by evolving aerospace production requirements, defense procurement, and demand across industrial, medical, and energy applications. As aircraft manufacturers work through record order backlogs, demand for aerospace-grade titanium bars, flat products, and tubes remains linked to production requirements across engines, airframes, and landing gear. At the same time, efforts to diversify titanium feedstock sources and strengthen domestic processing capabilities are creating investment opportunities across the value chain. However, price volatility, import tariffs, geopolitical uncertainties, and lengthy material-qualification cycles continue to challenge market participants, potentially increasing procurement costs and slowing supply-chain diversification, particularly for smaller fabricators and new entrants.
Increasing Commercial Aircraft Production and Fleet Replacement
Increasing commercial aircraft production and fleet replacement are driving demand in the global titanium alloys market. Titanium alloys are widely used in aircraft structures, landing gear, fasteners, and other components because of their high strength-to-weight ratio. Airbus delivered 793 commercial aircraft in 2025, up 4% from 2024, and ended the year with a backlog of 8,754 aircraft (Airbus, January 2026). As manufacturers increase production to meet accumulated orders, the requirement for aerospace-grade titanium alloys is supported by their strength and weight-saving benefits.
Growing Defense Aircraft Procurement and Modernization
Growing defense aircraft procurement and military fleet modernization are supporting demand for titanium alloys in the global defense sector. These alloys are used in selected aircraft structures, propulsion systems, and other weight-sensitive components that require high strength and reliable performance under demanding operating conditions. Global military expenditure reached USD 2.887 trillion in 2025, increasing 2.9% in real terms year over year (SIPRI, April 2026). Continued investment in military aviation and advanced defense platforms can support demand for high-performance titanium alloys, although overall military expenditure does not directly measure alloy consumption.
Expanding Medical Implant Applications
Expanding medical implant applications are creating additional demand opportunities for the global titanium alloys market. Titanium alloys, including Ti-6Al-4V ELI, are used in selected orthopedic implants because of their biocompatibility, mechanical strength, and corrosion resistance. According to the Organisation for Economic Co-operation and Development (OECD), average annual rates across reporting OECD countries reached 198 hip replacements and 156 knee replacements per 100,000 people in 2023 (OECD, Health at a Glance 2025). Rising joint replacement volumes support demand for implant materials, including medical-grade titanium alloys used in appropriate applications.
“As per our analyst, the global titanium alloys market is supported by demand for lightweight, high-strength materials across commercial aerospace and defense applications, while efforts to diversify qualified titanium feedstock sources and expand domestic processing capacity are reshaping global supply chains.”
Align with the Mega Trends Shaping the Industry. Get a Free Sample "Here".
High Production Costs and Machining Complexity of Titanium Alloys
High production costs and machining complexity remain key challenges for the global titanium alloys market. Titanium alloys have low thermal conductivity and retain high strength during machining, resulting in elevated cutting temperatures, faster cutting-tool wear, and lower machining speeds. These characteristics increase manufacturing time, tooling expenses, and the cost of finished components. In aerospace manufacturing, conventional forging and machining can require substantial material inputs relative to the final component weight, increasing material waste and processing costs. Consequently, the high cost of manufacturing titanium alloy components can limit their adoption in applications where more economical materials meet performance requirements.
Supply-Chain Concentration and Limited Availability of Aerospace-Grade Titanium Sponge
Supply-chain concentration and limited availability of aerospace-grade titanium sponge can create procurement risks for titanium alloy manufacturers. According to the European Commission's Joint Research Centre, China accounted for approximately two-thirds of global titanium sponge production in 2023, although much of its output was not suitable for critical aerospace applications. Aerospace-qualified sponge production is concentrated among a smaller group of suppliers, and stringent qualification requirements can make it difficult for manufacturers to switch sources quickly. This dependence can expose the titanium alloys supply chain to geopolitical disruptions, procurement delays, and raw-material price volatility.
"Flat products are expected to remain the leading product type, while tubes are projected to register the highest growth during the forecast period."
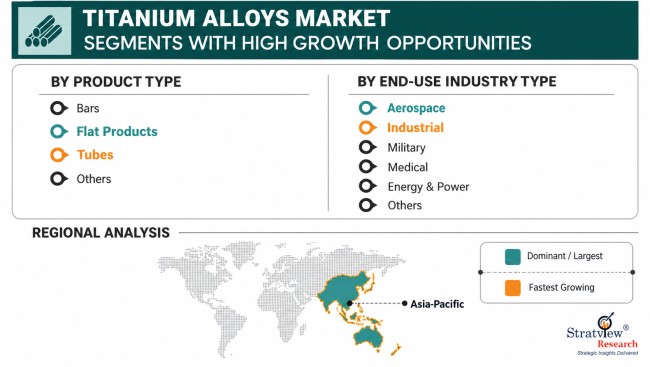
On the basis of product type, the global titanium alloys market is segmented into bars, flat products, tubes, and others. Flat products are expected to remain the leading product type, supported by their use in aerospace structural components and other applications requiring high strength and low weight.
Tubes are projected to register the highest growth during the forecast period, driven by demand for corrosion-resistant materials in selected oil and gas, chemical processing, and industrial applications where operating conditions require durable, high-performance components.
Get Insights on High-Growth Segments. Get a Free Sample "Here".
"Aerospace is expected to remain the dominant end-use industry, while industrial applications are projected to register the highest growth during the forecast period."
Based on end-use industry type, the global titanium alloys market is segmented into aerospace, industrial, military, medical, energy & power, and others. Aerospace is expected to remain the dominant end-use industry, supported by the use of titanium alloys in aircraft engines, compressor blades, discs, shafts, landing gear, fasteners, and structural components.
Industrial applications are projected to register the highest growth during the forecast period, supported by demand for materials that combine mechanical strength with corrosion resistance in selected chemical processing, marine, and specialized industrial equipment applications. Military, medical, and energy & power applications are also expected to contribute to demand through defense platform procurement, medical implant manufacturing, and specialized power-generation equipment.
"Asia-Pacific is expected to remain the largest regional market and register the fastest growth during the forecast period."
Asia-Pacific is expected to remain the largest and fastest-growing regional market for titanium alloys, supported by its established titanium production and processing capabilities, expanding aerospace manufacturing base, and demand from industrial applications. China and Japan play important roles in the regional titanium supply chain, while India and South Korea contribute through their aerospace, defense, and industrial manufacturing activities. These capabilities and end-use requirements are expected to support the region's market position throughout the forecast period.
North America is expected to remain the second-largest regional market, supported by its established aerospace and defense industries, major aircraft manufacturers, and specialized titanium alloy producers and processors. Demand from commercial aircraft manufacturing, military aviation, and high-performance industrial applications continues to support the region's consumption of titanium alloys, while efforts to diversify qualified material sources remain relevant to supply-chain resilience.
Speak to Us for Deep-Diving into a Country/Region-Specific Opportunity. Contact Us "Here".
The titanium alloys market includes several well-established metals and materials companies that supply bars, flat products, tubes, and other titanium mill products to aerospace, industrial, military, medical, and energy end users. Most major players compete on the breadth of their titanium product portfolio, melting and finishing capacity, long-term supply agreements with aerospace OEMs, and regional manufacturing presence.
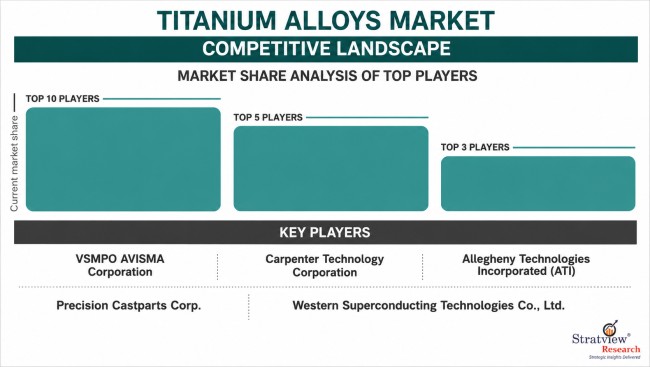
The following are the key players in the titanium alloys market.
VSMPO AVISMA Corporation
Carpenter Technology Corporation
Allegheny Technologies Incorporated (ATI)
Precision Castparts Corp.
Western Superconducting Technologies Co., Ltd.
Note: The above list is not an exhaustive list of the key players in the market. If your company is active in this market and would like to be considered for inclusion in future editions of this study, please contact us at [email protected].
Have the Competitive Edge with Our Intelligence. Get a Free Sample "Here".
ATI June 2025 - New titanium alloy sheet facility begins production
ATI brought its new facility in Pageland, South Carolina, online to produce titanium alloy sheet for aerospace structures. The integrated facility includes finishing, inspection, and processing capabilities, expanding ATI's portfolio of titanium products for airframe manufacturers. ATI stated that more than two-thirds of the facility's capacity was expected to be covered by long-term agreements with aerospace customers, with qualifications underway.
ATI May 2025 - Multi-year titanium supply agreement with Airbus
ATI signed a multi-year agreement to supply titanium plate, sheet, and billet to Airbus, more than doubling ATI's previous support under the arrangement. The agreement supports Airbus's narrowbody and widebody aircraft production and strengthens ATI's position as a supplier of titanium flat-rolled and long products.
ATI July 2025 - Expanded titanium supply agreement with Boeing
ATI extended and expanded its long-term agreement with Boeing to supply titanium materials across commercial aircraft programs. The contract covers ingots, billets, bars, plate, sheet, and coil, including products from ATI's new Pageland facility.
The titanium alloys market encompasses titanium-based metal products containing a higher proportion of titanium combined with other metals such as aluminum and vanadium to deliver exceptional corrosion resistance, high-temperature resistance (up to approximately 550°C for select alloys), and a superior strength-to-weight ratio compared with conventional metals. The most widely used titanium alloy, Ti-6Al-4V, is extensively applied across aerospace ducting, hydraulics, tubing, and airframe components, as well as military, marine, and consumer applications. Manufacturers supply titanium alloys in the form of bars, flat products, tubes, and other mill products for use across the aerospace, industrial, military, medical, and energy & power industries.
This report provides the most comprehensive market intelligence. The report structure has been kept so that it offers maximum business value. It provides critical insights into market dynamics and will enable strategic decision-making for existing market players and those looking to enter the market.
The following are the key features of the report:
Market structure: Overview, industry life cycle analysis, supply chain analysis.
Market environment analysis: Growth drivers and constraints, Porter's five forces analysis, SWOT analysis.
Market trend and forecast analysis.
Market segment trend and forecast.
Competitive landscape and dynamics: Market share, product portfolio, new product launches, etc.
Attractive market segments and associated growth opportunities.
Emerging trends.
Strategic growth opportunities for the existing and new players.
Key success factors.
|
Market Study Period |
2020-2034 |
|
Base Year |
2025 |
|
Forecast Period |
2026-2034 |
|
Trend Period |
2020-2025 |
|
Number of Tables & Figures |
100+ |
|
Number of Segments Analysed |
3 (Product Type, End-Use Industry Type, and Region) |
|
Number of Regions Analysed |
4 (North America, Europe, Asia-Pacific, Rest of the World) |
|
Countries Analysed |
17 (The USA, Canada, Mexico, Germany, France, The UK, Russia, Spain, Rest of Europe, China, Japan, India, South Korea, Rest of Asia-Pacific, Saudi Arabia, Brazil, and Rest of the World) |
|
Free Customization Offered |
10% |
|
After Sales Support |
Unlimited |
|
Report Presentation |
Complimentary |
|
Market Dataset |
Complimentary |
|
Further Deep Dive & Consulting Services |
10% Discount |
Want a Report Tailor-Made to Your Objectives? Speak with Our Analyst.
The report provides detailed insights into market dynamics to enable informed business decision-making and the formulation of growth strategies based on market opportunities.
The titanium alloys market is segmented into the following categories:
Titanium Alloys Market, By Product Type
Bars
Flat Products
Tubes
Others
Titanium Alloys Market, By End-Use Industry Type
Aerospace
Industrial
Military
Medical
Energy & Power
Others
Titanium Alloys Market, By Region
North America (Country Analysis: The USA, Canada, and Mexico)
Europe (Country Analysis: Germany, France, The UK, Russia, Spain, and Rest of Europe)
Asia-Pacific (Country Analysis: China, Japan, India, South Korea, and Rest of Asia-Pacific)
Rest of the World (Country Analysis: Saudi Arabia, Brazil, and Others)
Looking for a Deep Dive? Speak with Our Analyst.
This strategic assessment report from Stratview Research provides a comprehensive analysis that reflects today's titanium alloys market realities and future market possibilities for the forecast period.
The report segments and analyzes the market in the most detailed manner to provide a panoramic view of the market. The vital data/information provided in the report can play a crucial role for market participants and investors in identifying the low-hanging fruits available in the market and formulating growth strategies to expedite their growth process.
This report offers high-quality insights and is the outcome of a detailed research methodology comprising extensive secondary research, rigorous primary interviews with industry stakeholders, and validation and triangulation with Stratview Research's internal database and statistical tools.
More than 1,000 authenticated secondary sources, such as company annual reports, fact books, press releases, journals, investor presentations, white papers, patents, and articles, have been leveraged to gather the data.
We conducted more than 15 detailed primary interviews with market players across the value chain in all four regions and industry experts to obtain both qualitative and quantitative insights.
With this detailed report, Stratview Research offers one of the following free customization options to our respected clients:
Company Profiling
Detailed profiling of additional market players (up to three players).
SWOT analysis of key players (up to three players).
Competitive Benchmarking
Benchmarking of key players on the following parameters: product portfolio, geographical reach, regional presence, and strategic alliances.
Custom Research: Stratview Research offers custom research services across industries. In case of any custom research requirement related to market assessment, competitive benchmarking, sourcing and procurement, target screening, and others, please send your inquiry to [email protected].
The report is delivered digitally through our online portal. Buyers receive login credentials from our team to access the report and may update their credentials at any time after the initial login.
Delivery timelines depend on the status of the report:
For the most accurate delivery timeline, please contact us to confirm the current status of the report.
Yes. You may request a complimentary preview of the report through a video conference with our team.
Yes. The scope of the report can be fully customized to align with your specific research objectives and information requirements.
Please contact us at [email protected], and our team will be happy to discuss your requirements and propose a tailored solution.
Yes. Selected sections of the report can be purchased separately based on your requirements. Please contact us at [email protected] to discuss your needs.
Yes, AI can help gather publicly available information, but its outputs are only as reliable as the data it accesses. Stratview Research reports are built using validated data, extensive primary interviews with industry stakeholders, and the expertise of our experienced research team.
Additionally, many critical insights, including market dynamics, competitive intelligence, and industry-specific trends, are not publicly available and therefore cannot be captured through AI alone.
Titanium alloys market size was USD 7.62 billion in 2025. The market is expected to grow from USD 8.07 billion in 2026 to USD 11.68 billion in 2034, witnessing a steady market growth (CAGR) of 4.7% during the forecast period (2026-2034).
Asia-Pacific holds the largest share in the titanium alloys market, supported by its established titanium production ecosystem and the presence of leading aerospace, shipbuilding, and industrial manufacturers in the region.
VSMPO AVISMA Corporation, Carpenter Technology Corporation, Allegheny Technologies Incorporated (ATI), Precision Castparts Corp., and Western Superconducting Technologies Co., Ltd. are the leading players in the titanium alloys market.
Industrial applications are projected to record the highest growth among all end-use industries in the titanium alloys market in the coming years, driven by titanium's corrosion resistance and its growing adoption across the chemical processing industry.

WE ACCEPT